



FILTERED RESULTS
FILTERS
MCap $2.9T +0.1%24h Vol $100.6B -6.8%Fear & Greed 74/100Alts Index 51/100
BTC.D 58.4% 0%Stable.D 9.2% 0%ETH.D 11.4% 0%Others.D 21.0% 0%
TRAC$0.4684+24.99%•NIGHT$0.0404+23.54%•STONK$0.2919+22.27%•STX$0.3860+21%•MON$0.0323+19.09%•SOON$0.4970+18.03%•CAP$0.0696+14.87%•S$0.0416+9.65%•PROS$0.7374+9.37%•QNT$294.50+9.07%•
AI$0.1811-13.33%•TIBBIR$0.2944-12.76%•BTW$1.158-11.27%•BR$0.7593-10.7%•MARSCOIN$0.1352-9.14%•2Z$0.0595-8.92%•BP$1.207-8.52%•SYRUP$0.2259-5.93%•AR$4.087-5.39%•COMP$24.745-5.34%•
•
·
·
FILTERED RESULTS
Grayscale: XRP’s Near-6% Bitcoin Valuation Sets a Benchmark for Zcash
Cardano Hits $0.25 on Petrobras Adoption: Next ADA Buy Zone Revealed
Ancient Ethereum whale moves $356 million worth of ETH to a new address
Bybit Releases 40th Proof-of-Reserves ReportBybit released its 40th proof-of-reserves report based...
A whale withdrew 39,018 AAVE worth $6.2 million from Kraken 3 hours ago
Bybit Reports $19.6 Billion in Proof-of-Reserves Following Expansion of Asset Coverage
Morgan Stanley's total Bitcoin holdings surpass 10,000 BTC for the first time, worth over $870 million
CFTC seeks to define event contracts as swaps amid prediction market fight
514,175 $HYPE (46,282,266 USD) transferred from #HyperCore to #Kinetiq...
Robinhood CEO on stock token roadmap: Covering thousands of companies and exploring private equity tokenization
156,300,000 $USDC (156,362,520 USD) transferred from Unknown Whale 1 to #Aave...
Cryptocurrency Market Financing Reaches $1.114 Billion in September 2026
400,000,000 $XRP (595,636,565 USD) unlocked at #Ripple...
Solana treasury company HSDT completes $15 million share offering, to buy more SOL or repurchase shares
ESMA proposes expanding MiCA scope to cover DeFi entry points, staking and crypto lending services
U.S. SEC Files Lawsuits Against Two Private Equity Funds for Fraudulent Practices
Ripple Unlocks 1 Billion XRP Valued at Approximately 1.49 Billion USD
Hyperliquid dev team HyperLabs address requests redemption of 3.75 million HYPE
200,000,000 $XRP (297,818,282 USD) unlocked at #Ripple...
Uphold Adds XRP, Bitcoin Inheritance, Citing $331 Billion Stranded
TD Cowen says Bitcoin is evolving from an asset into a capital markets...
Spot silver falls below the $60 mark
Arthur Hayes: Hyperliquid Is the Best DEX, but Not Necessarily the Most Profitable InvestmentFlop...
MetaMask exits Lido validators as it investigates security incident
300,000,000 $XRP (446,727,424 USD) unlocked at #Ripple...
MetaMask Staking Withdraws from Lido Validators Following Security Breach
Ripple Unlocks 1 Billion XRP in One Go, Worth About $1.49 Billion
MetaMask said it has identified a security incident affecting part of its
KLEA Crypto Daily: Wednesday, September 30, 2026
MetaMask: Security Incident Affects Part of Infrastructure, No Immediate Threat to Wallets...
AvengerDAO Security Marketplace Expands to 17 Firms with New Additions
100,000,000 $XRP (148,909,141 USD) unlocked at #Ripple...
Fed's Kashkari: Expects one more rate hike this year and another in 2027
METAMASK CURRENTLY RESPONDING TO ONGOING SECURITY INCIDENT, SAYS THERE IS NO THREAT TO WALLETS:...
Aave Founder: Closely Monitoring MetaMask Staking Incident, Aave Markets Unaffected
Lido: MetaMask Staking to exit its operated validator nodes, expected to complete before October 7, 2026
MetaMask Staking Exits Lido Validators Amid Security Concerns
1,611 $BTC (134,647,322 USD) transferred from #Kraken to unknown wallet...
METAMASK RESPONDING TO SECURITY INCIDENT; NO THREAT TO METAMASK WALLET AND METAMASK CURRENTLY...
156,300,000 $USDC (156,330,400 USD) transferred from #Aave to Unknown Whale 1...
MSCI Rule Puts Strategy at Risk, Says Bitcoin Policy Institute Paper
NEAR Traders on Hyperliquid Face Significant Losses Amid Market Rally
Gemini 4 Is Here, and Google’s Flagship Tops All Other AI Models on Cybersecurity
Robinhood to Launch Crypto Perpetual Futures in the US
Brazil’s largest energy giant tests Cardano to fix carbon double-counting
Swiss National Bank Raises Concerns Over Stablecoins' Impact on Monetary Policy
Animoca Brands’ Moca Chain Takes Aim at Digital Identity
Crypto and TradFi Are Converging Faster Than Their Business…
Trump calls for Jerome Powell to resign from the Fed Board over the...
Standard Chartered says Ethena’s ENA could crush Bitcoin and Ethereum returns by 2028
Bitcoin Approaches Positive September Close Amid Market Dynamics
Dogecoin Is Getting Apps as DogeOS Opens Its Public Testnet
Coinbase-Backed Base Gives Users More Control With Cobalt Upgrade
250,000,000 $USDC (250,044,375 USD) minted at USDC Treasury...
U.S. Treasury Department Sanctions Tren de Aragua ATM Network and Identifies Tron Addresses
1,000 $BTC (83,746,919 USD) transferred from Coinbase Institutional to unknown wallet...
FBI Tells Its Employees to Assume Hackers Have Their Personal Data
Mellow to Wind Down Autopilot as Aerodrome Prepares for Aero Launch
Bitcoin Bull Market Shows Signs of Cooling: CryptoQuant
Bitget’s hackers turn to Zcash after $50 million laundering route gets blocked
Standard Chartered sees Ethena’s USDe reaching $40B, ENA hitting $2
Bitcoin Price Holds $83K as Bitfinex Says Leverage Has Cleared
Coinbase-Backed Crypto Group Reveals Midterm Endorsements After Clarity Act Collapse
Base Launches Cobalt Upgrade With New Trading and Tokenization Tools
U.S. Treasury Sanctions 10 TdA-Linked Targets Over ATM Jackpotting
Binance Pay Enables Crypto Spending at PayPay Merchants…
Monarch Wallet Review: How the Multi-Asset Crypto App…
Top Trending Coins (Today) 1. QNT 2. TRUMP 3. EDEL 4. NEAR 5. BP 6. PENGU 7. LIT 8. HYPE 9. BTC...
CFTC Submits Prediction Market Rules to White House for Review
Bitcoin self-custody creates a massive cost-basis blind spot on your 2026 crypto tax forms


A Bitcoin investor can withdraw coins from an exchange, return them to the same account, and still fall outside mandatory cost-basis reporting when those coins are sold.
For the 2026 US reporting year, the broker can still be required to report sale proceeds, while reporting the acquisition cost remains voluntary.
Cost basis, the acquisition cost used to calculate a gain, only changes the broker's obligation to supply an ordinary transfer between the investor's own accounts. That creates a practical divide between a record showing how much a sale brought in and one that supports the gain calculation.
The IRS's 2026 Form 1099-DA instructions make that divide explicit. Covered digital assets generally must have been acquired after 2025 in the reporting broker's custodial account and held there until disposal. Assets bought before 2026 or transferred into the broker are noncovered, with basis reporting voluntary.
The distinction runs through the current reporting year as international reporting develops and blockchain analytics providers offer tax authorities a wider view of activity.
Three routes, the same gain
Consider a deliberately simplified hypothetical US investment: 0.1 Bitcoin bought for $5,000 in February 2026 and sold for $7,000 in September. Assume one purchase lot, unchanged ownership, no intervening trades, no fees, and no other basis adjustments.
The purchase and sale stay identical across three paths, only the custody route changes.
| Custody route | 2026 reporting classification | Basis and gain in this example |
|---|---|---|
| Bought and continuously held with the selling broker | Covered; mandatory basis reporting | $5,000 basis; $2,000 gain |
| Bought with one broker, transferred to another and sold | Noncovered; basis reporting voluntary | $5,000 basis; $2,000 gain |
| Bought with a broker, withdrawn to an owned wallet, returned and sold | Noncovered; basis reporting voluntary | $5,000 basis; $2,000 gain |
The third path is the easiest to miss. Returning to the original account does not satisfy the continuous-custody condition. A broker may have recorded the original purchase, but that does not make returned coins continuously held assets under the reporting definition.
For the investor, each hypothetical sale still produces the same $2,000 gain. A blank basis field cannot be read as a $7,000 gain, so the missing information on the form does not determine that the acquisition cost was zero.
The IRS's digital-asset FAQs explain why the wallet movement itself does not change that result: transferring assets between accounts or wallets belonging to the same taxpayer is nontaxable, except for digital assets used or withheld to pay for transfer services.
Fee coins can create a separate disposal, which is why the comparison deliberately excludes fees.
Outside applicable optional reporting methods, the form includes fields for transferred units subsequently disposed of and their transfer-in date, with a date exception for transfers on varied dates. Sale proceeds can be reportable even when basis is not mandatory.
Coinbase's current guidance distinguishes its proceeds-only 2025 forms from basis information beginning in tax year 2026 for certain assets. It also tells customers to retain records from other accounts and wallets. That qualification matters: the change does not promise a completed basis record for every sale.
Kraken's guide to its 2025 combined forms, updated March 30, describes a more specific split. Customer copies showed estimated basis and gains or losses using FIFO, or first in, first out. What was sent to the IRS was the gross proceeds.
The same guide says Kraken tracks basis for activity within the same account, does not track what happens outside it, and treats returning assets as a new deposit without automatically restoring their previous basis.
For the unchanged lot in this hypothetical, recording its return as a new deposit does not create a new acquisition cost. The original purchase record remains relevant even if the returning deposit lacks an automatically attached basis.
This distinction gives investors three separate questions to resolve: what the platform displays, what it reports to the authority, and what their full transaction history supports. A convenient gain estimate may answer only the first.
Why a wider Bitcoin transaction trail still needs acquisition records
International reporting addresses a different part of the problem. The OECD's Crypto-Asset Reporting Framework (CARF) provides for annual exchange of crypto-transaction information with taxpayers' residence jurisdictions through domestic rules and exchange arrangements. It is separate from US Form 1099-DA and does not create a single worldwide crypto tax bill.
The UK offers a concrete timetable. HMRC's guidance calls for user details and transaction summaries, with the first provider report due between Jan. 1 and May 31, 2027, covering calendar 2026.
That reporting can reveal transactions without attaching the acquisition history needed for every investor's gain.
Blockchain analytics extends the question beyond broker submissions. In an Aug. 26 research preview, Chainalysis estimated more than $457 billion in potentially taxable on-chain activity during 2025, including approximately $112.6 billion attributed to the US.
The commercial analytics provider says it covers Bitcoin, Ethereum, Solana, Tron, BNB Smart Chain and Base, assigning countries through direct location signals and proportional allocation based on service activity.
Its estimate excludes trading, staking, and lending conducted inside centralized exchanges and does not apply some countries' transaction or income exemptions. Missing activity restricts coverage, while unapplied exemptions prevent treating every estimated dollar as taxable in its assigned jurisdiction.
Address tracing can help connect movements. However, a path between addresses does not establish an investor's purchase price, unchanged ownership, chosen acquisition lot or subsequent adjustments.
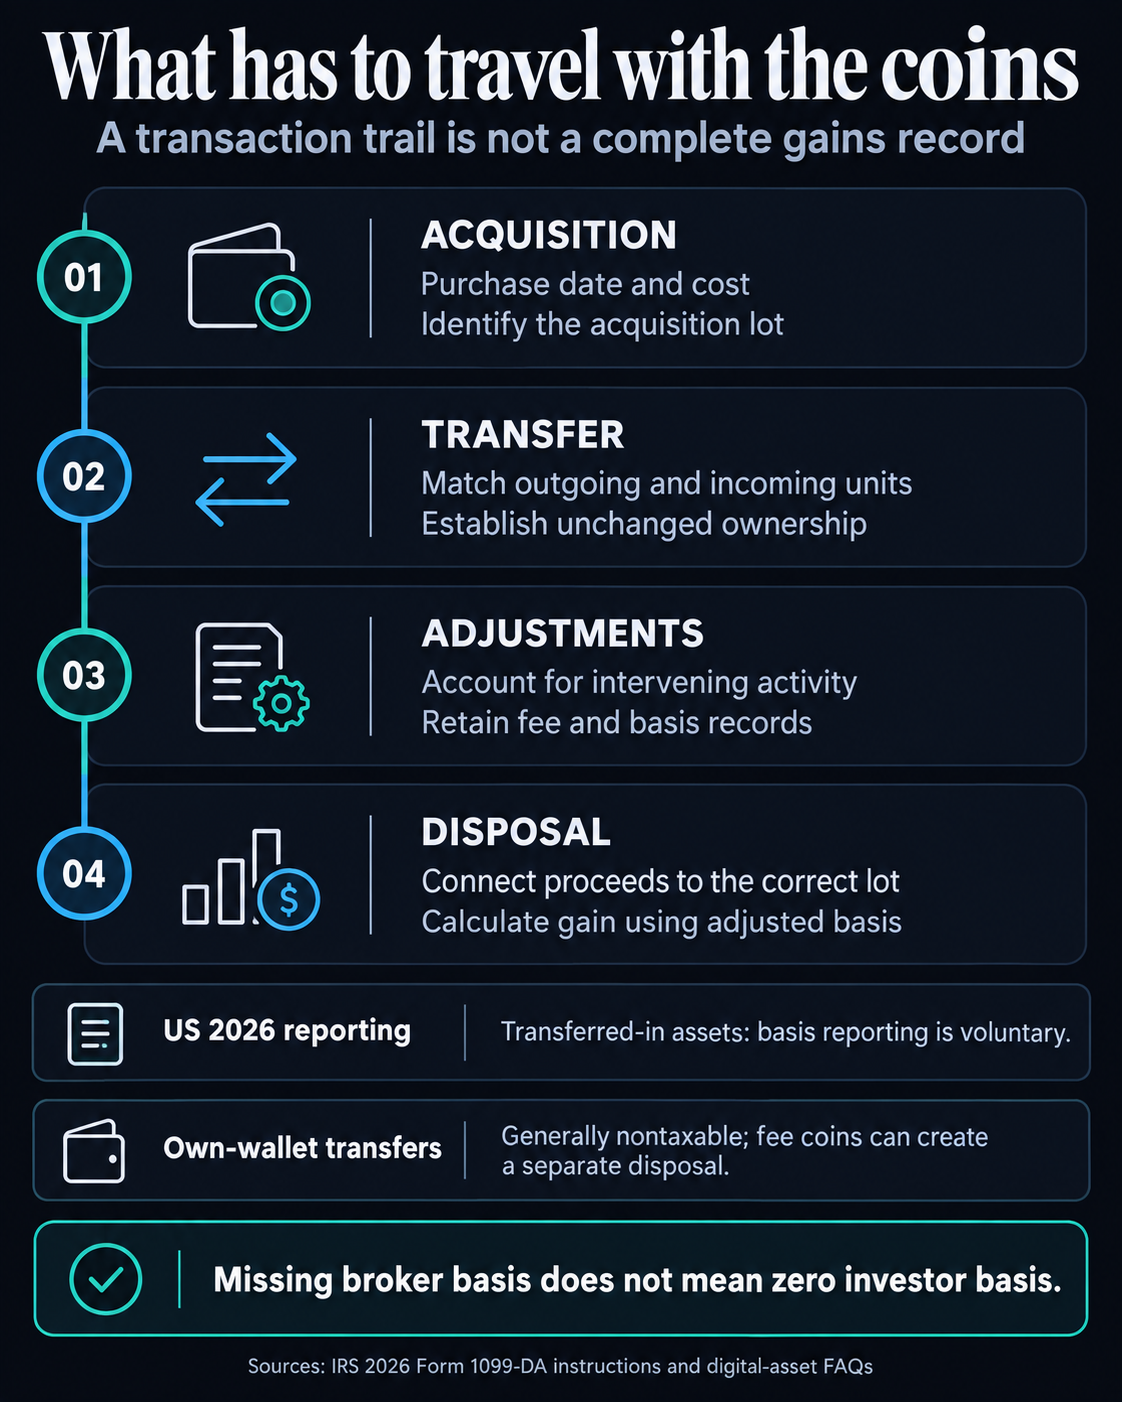
For the US investor in the three-route comparison, a usable gains record needs continuity of information and continuity of ownership. In the three-route example, the crucial connection is between the original $5,000 purchase and the eventual disposal. An incoming transfer's date and quantity alone do not make that connection.
Better interoperability would need to preserve acquisition details, match outgoing and incoming transfers, and account for intervening disposals and adjustments. That could reduce reconstruction work without requiring every investor to remain in one account. Sharing those records would not make the transferred lots continuously held assets under the current rule.
For relevant partial disposals after 2025, IRS FAQ 85 requires investors using specific identification to identify units to the custodial broker by transaction time using its designated identifiers and retain substantiating records. A later spreadsheet choice does not substitute for timely identification.
The reporting rules also contain exceptions: eligible optional methods for qualifying stablecoins and specified NFTs can omit basis even for covered assets, and certain categories have reporting thresholds. Assess a form's completeness based on the method used.
The available disclosures establish why more reporting can coexist with unfinished records. For a transferred holding, calculating the gain still means connecting the sale to the original acquisition, the correct lot, and any subsequent adjustments.
Source: CryptoSlate