



FILTERED RESULTS
FILTERS
MCap $2.9T -0.1%24h Vol $113.1B -27%Fear & Greed 71/100Alts Index 57/100
BTC.D 58.4% +0.1%Stable.D 9.3% +0.1%ETH.D 11.4% 0%Others.D 20.9% -0.2%
QNT$293.98+40.97%•SOON$0.4010+35.88%•GRASS$0.7412+29.09%•PUMP$0.00586976+24.18%•NIGHT$0.0325+16.81%•ZBCN$0.00256529+16.72%•ZRO$1.738+16.47%•ETHFI$0.7730+14.43%•COMP$26.296+13.4%•PENGU$0.0101+11.94%•
HBAR$0.1028-12.65%•LIT$3.831-11.52%•AI$0.1982-9.26%•BR$0.8281-8.92%•MARSCOIN$0.1462-7.15%•ALGO$0.1249-6.38%•BTW$1.302-6.08%•Q$0.0235-5.94%•ZAMA$0.0733-5.41%•PROM$5.955-4.95%•
•
·
·
FILTERED RESULTS
Trader Killa: Market's expected deep pullback may not materialize, still bullish on Bitcoin toward the $90,000 range
Maelstrom CIO Arthur Hayes said at Korea Blockchain Week 2026 that no digital currency —
Abracadabra Proposes Liquidation Agreement for MIM Stablecoin Holders
DeepSeek Open-Sources Infrastructure for Huawei Ascend Computing Platform
Binance Pay Brings PayPay QR Payments to Tourists in Japan with Limited-Time 10% Discount!Binance is...
750 $BTC (62,660,077 USD) transferred from unknown wallet to Coinbase Institutional...
Abracadabra Proposes Winding Down Magic Internet Money at Four Cents on the Dollar
Brazil's CSD BR Collaborates with Ripple to Integrate Securities Records on XRP Ledger
Bitget Releases 47th Proof of Reserves, Composite Reserve Ratio Across 19 Asset Classes Reaches 131%
Abracadabra Proposes Liquidation of MIM at Four Cents on the Dollar
250,000,000 $USDC (250,033,000 USD) minted at USDC Treasury...
Ripple Brings XRP Ledger to Brazil’s BRL 22 Trillion Asset System
Binance Will Support the Ronin (RONIN) Network Upgrade & Hard Fork - 2026-10-07Starting at appro...
Velocity (formerly Drift Protocol) co-founder Cindy resigns; exchange restarts after rebuilding following hack
171,900,000 $USDC (171,922,604 USD) transferred from Unknown Whale 1 to #Aave...
171,900,000 $USDC (171,921,917 USD) transferred from #Aave to Unknown Whale 1...
Whale 0x9a80, who bought 30M $ENA($8.3M) 3 days ago, bought another 7.96M $ENA($1.99M)...
Whale that bought 30 million ENA three days ago buys another 7.96 million
100,000,000 $USDC (100,015,350 USD) transferred from #Ethena to unknown wallet...
Arrington Capital transfers $3.44 million worth of HYPE to FalconX
Multicoin Capital announces investment in DePIN project Grass, which generated $17 million in revenue in the first half of 2025 and 2026 respectively
XRP Seoul Brings Tokenization, Yield, and Privacy Firms Together
986 $BTC (82,446,607 USD) transferred from unknown wallet to Coinbase Institutional...
Kalshi is ending its volume incentive program, effective no earlier than Oct. 13,
Kalshi Ends Volume Incentive Program Effective October 13, 2026
1,827 $BTC (152,513,055 USD) transferred from #Paypal to unknown wallet...
Quant Network founder moves about 25,800 QNT worth $6.97 million after 7 years of dormancy
Quant Network founder wallet 0x48E9 moved 25,776 $QNT($6.97M) to new wallets after 7 years of...
1,826 $BTC (152,396,197 USD) transferred from unknown wallet to #Paypal...
Sentora split 50% Aave revenue, but suppliers absorb all losses
Robinhood is launching in-app perpetual futures trading in coming months, allowing
LIT briefly falls below $3.7, with $6.86 million liquidated in 4 hours
Robinhood Introduces 10x Leveraged Crypto Trading for US Users
Machi closes PUMP long for $827,000 profit, then opens $5.26 million 10x leveraged long
1,333 $BTC (111,291,916 USD) transferred from unknown wallet to unknown wallet...
Anthropic Research Highlights Zhipu GLM-5.3's Network Utilization Capabilities
VelocityDEX Launches After Audit Completion Amid Co-Founder Departure
Michael Saylor Sees $100T Digital Asset Industry With Rule Changes
Machi (@machibigbrother) closed his $PUMP long 9 hours ago, realizing a $827K profit.Right after...
1,332 $BTC (111,225,164 USD) transferred from unknown wallet to unknown wallet...
Grayscale's ETF adds $2.36 million worth of LINK
Project Eleven Acquires Riva Labs to Strengthen Post-Quantum Security Research and Engineering Capabilities
SEC sues Cryptoaiml and TSAI over alleged $15 million AI trading scam...
Binance Co-CEO Highlights Early Signs of Recovery Amid Economic Challenges
CZ: Industry Pioneers Don’t Always Remain the Biggest Winners On September 25, 2026, Binance...
177,614,496 $USDC (177,636,521 USD) transferred from unknown wallet to #Coinbase...
Robinhood to launch AI agents, 10x leverage crypto perpetual contracts, and weekend US stock trading
Fake Coinbase Texts Led to $900K Bitcoin Theft, US Seeks Seized Crypto
KLEA Crypto Daily: Tuesday, September 29, 2026
Crypto Fear and Greed Index Index Value : 71 Sentiment : Greed BTC Price : $83660 ...
153,139,246 $USDC (153,192,845 USD) transferred from Coinbase Institutional to...
Project Eleven Acquires Riva Labs to Enhance Post-Quantum Security Capabilities
Stride Proposes Orderly Shutdown of Its Liquid Staking Chain
Zano Network Stabilizes After 30-Day Blockchain Rewind to Fix Inflation Bug...
RobinhoodApp ANNOUNCES PERPS ARE ROLLING OUT FOR U.S. TRADERS ...
618 $BTC (51,432,007 USD) transferred from Coinbase Institutional to unknown wallet...
Robinhood Launches Cryptocurrency Perpetual Contracts in the US
749 $BTC (62,330,840 USD) transferred from unknown wallet to Coinbase Institutional...
Robinhood To Offer Perps In-App Using Bitstamp: Press Release ...
Robinhood Introduces AI Trading Agents and New Trading Features
SEC charged Cryptoaiml Ltd., Cryptoaiml Capital Foundation, as well as TSAI Pro Ltd.
Bitcoin Was the Asset. Now Institutions Are Building Around It
5,035 $BTC (418,671,285 USD) transferred from Coinbase Institutional to unknown...
CryptoQuant says a bitcoin correction could be near after traders' unrealized profit
Robinhood adds AI agents, perps and weekend trading in push to win active traders
Hut 8 locks in $1B credit line, but faces 40% liquidity rules
1,551 $BTC (129,069,580 USD) transferred from unknown wallet to Coinbase...
Aztec relaunches privacy wallet on its Ethereum Layer 2
1,816 $BTC (151,093,512 USD) transferred from unknown wallet to Coinbase...
The fight over Ethereum’s supply is forcing a choice between high staking yields and the value of your ETH


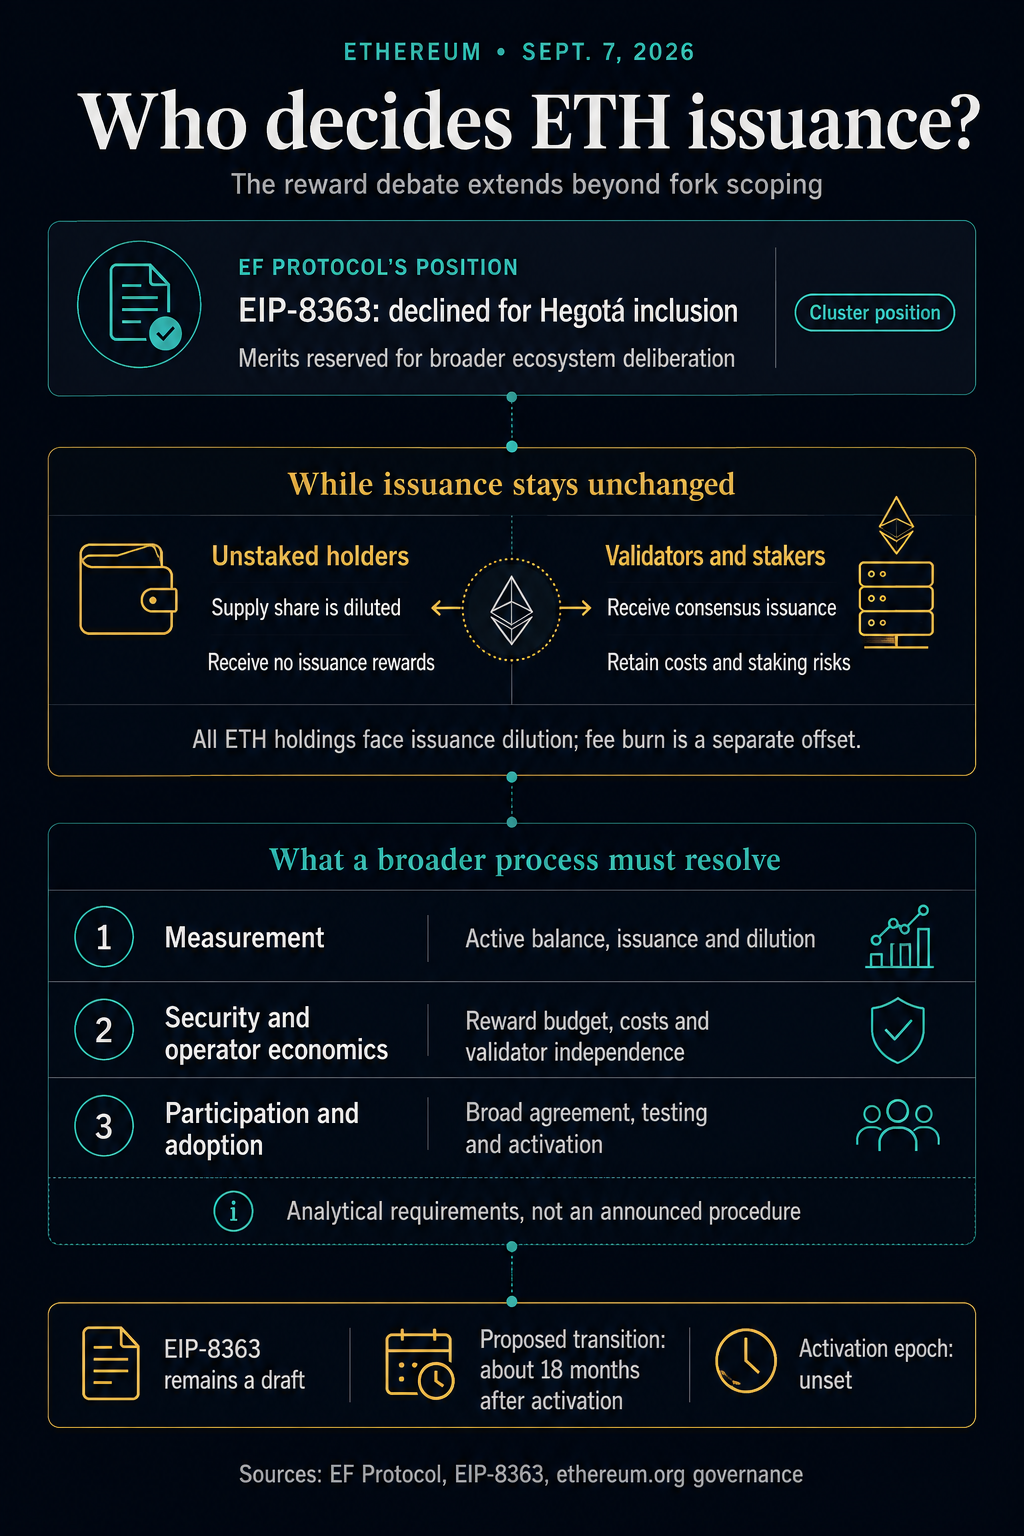
The Ethereum Foundation’s Protocol cluster says Ethereum’s issuance policy belongs in a broader ecosystem process than fork scoping.
In its Sept. 7 assessment of proposals for the Hegotá upgrade, EF Protocol graded EIP-8363, a proposal to burn part of validators’ issuance rewards, as declined for inclusion in its own priorities. Its four graders were unanimous. But the cluster reserved judgment on the proposal’s merits and called for a broader ecosystem process, saying policy affecting stakers, holders and the network’s security budget requires participation beyond EF Protocol.
That leaves an economic choice running while the governance question remains open. Existing issuance continues to dilute holdings while compensating validators; unstaked holders bear that dilution without receiving issuance rewards. Cutting it would reduce that dilution, but the claim that doing so would protect smaller operators remains contested. The task for Ethereum is to decide both how much security to pay for and whose evidence and consent can justify changing the bill.
What unchanged issuance costs
New ETH issued to validators expands the supply against which every holding is measured. Those issuance rewards go to stakers, leaving unstaked holders exposed to dilution. Stakers also experience dilution, but receive issuance in return for participating in consensus and retaining the associated risks.
The holder keeps the same number of ETH, but owns a smaller share of the expanded supply. Ethereum’s base-fee burn can offset issuance. Net supply growth depends on both flows; ETH’s market return remains a separate measure.
The current staking picture makes that distinction consequential. Validator Queue, retrieved at 15:37 UTC on Sept. 7, showed 42.9 million ETH staked, or 35.13% of supply. Another 1,975,361 ETH was waiting to enter, with a displayed wait of 34 days and seven hours. Pending ETH remains in the entry queue until validator activation.
The displayed share is consistent with the 122.03 million ETH supply on CryptoSlate’s Ethereum page: 35.13% of that total is about 42.87 million ETH. These rounded dashboard figures establish an approximate staking share; the proposal’s calculation requires the exact active effective balance. Applying a reward-cut percentage directly to them would imply more precision than the measurements support.
To compare the issuance paid to validators with the dilution borne by holders, the calculations below use three explicit scenarios around the displayed staking share. Each assumes perfect participation, a constant active balance and 122.03 million ETH as the starting supply reference. They exclude compounding, execution income, fee burn, costs, taxes and penalties. They illustrate annualized policy effects under those assumptions; future staking participation remains variable.
| Hypothetical active stake / starting supply | Current consensus APR | Gross annual issuance / starting supply | Proposed consensus APR after transition |
|---|---|---|---|
| 30% | 2.75% | 0.82% | 1.45% |
| 35% | 2.54% | 0.89% | 1.03% |
| 40% | 2.38% | 0.95% | 0.64% |
Source: CryptoSlate calculations using the EIP-8363 formulas and the supply reference above. Proposed returns use the draft’s fixed 60.25 million ETH saturation balance.
Under the existing curve, more active stake lowers the reward rate per ETH while increasing total issuance. In the 35% scenario, about 1.086 million ETH would be issued over a year. Before fee burn, an unchanged unstaked holding’s share of supply would fall by about 0.88%.
For a performing 32 ETH stake, the same scenario produces about 0.81 ETH in annual consensus rewards before expenses and penalties. That is the distribution preserved by leaving policy unchanged: holders who remain unstaked bear dilution without receiving the issuance that compensates validators.
The reward cut and the solo-validator test
EIP-8363 remains a draft. It would deduct and burn a fraction of idealized rewards for assigned consensus duties. The fraction rises with active balance until issuance is offset at the saturation threshold.
The specification lists that threshold as 60.25 million ETH, intended to represent roughly half the supply at the fork. That fixed balance stays in place as supply changes, so its percentage of total supply can drift. That distinction matters when estimating the size of a cut.
The proposed transition also matters. At activation, the base reward factor would rise from 64 to 128 and then return to 64 over approximately 18 months. That temporary increase cushions the change, with initial returns varying by staking level. In the illustrative 35% case, consensus APR would begin near 2.05% and reach about 1.03% after the transition, compared with 2.54% under the existing formula.
The corresponding 32 ETH annual consensus reward would be about 0.33 ETH after the transition. That comparison holds stake constant to isolate the policy effect. Actual participation could change in response.
MEV and execution priority fees would remain outside this issuance burn. Additional staking would remain possible at the saturation balance, and validators could still receive execution income. The proposal changes the issuance component of compensation, and its activation epoch is unset.
The case for reducing issuance is broader than saving holders dilution. The EIP’s proponents argue that rising staking participation could increase dependence on custodians and other intermediaries, making Ethereum more vulnerable to capture. The argument centers on who controls the stake and how that control affects Ethereum’s independence.
The opposing case challenges whether cutting rewards improves that composition. In the public discussion, participant goodroot questioned whether higher-cost solo operators would become uneconomic before large providers able to spread costs across more validators. Participant vshvsh likewise warned that worsening operator economics could increase concentration.
Resolving that dispute requires evidence about operator costs as well as reward revenue. Operating costs determine how much of that revenue becomes profit, and those costs vary even when the protocol treats validators equally. The same reduction in rewards could have different consequences for an independent validator and an intermediary managing many customers’ stakes.
The interests of holders and stakers overlap. Stakers own ETH too, so they also benefit from less dilution. Unstaked holders, meanwhile, depend on the security that rewards help fund. A credible decision must weigh those overlapping interests rather than treat either lower issuance or preserved yield as a sufficient measure of success.
Who can authorize the change?
Ethereum’s documented governance process is offchain and includes holders, application users and developers, node operators, validators and protocol developers. Community consensus involves broad participation rather than any single measure, including a coin vote. Writing a specification, agreeing to include it and activating tested software are separate steps.
Against that background, EF Protocol’s position creates a practical test for the broader process it wants. Participants need a shared baseline for active stake and issuance, evidence about the security budget, and an account of how different operator costs affect survival. Otherwise, the same reward calculation can be presented as either protection against concentration or a reason to expect more of it.
Representation matters for the same reason. A process dominated by reward recipients could underweight the dilution borne elsewhere; one focused only on scarcity could underweight the costs of operating the network. A deliberative process needs to account for both risks without assuming either group has captured the decision.
Solana offers a useful distinction between endorsement and execution. Its SGP-0002 governance proposal is marked Accepted, but explicitly depends on acceptance and activation of SIMD-0550. The technical document remains marked Review, with its feature key and implementation tracking unset in the Sept. 7 record.
That specification describes preserving the inflation rate at the activation boundary before applying faster disinflation, with consistent client calculations required. The governance label establishes endorsement; implementation and activation remain separate requirements. Ethereum likewise needs a visible route from broad agreement to implementation, testing and activation before holders can treat changed rewards as policy.
EF Protocol has announced a Sept. 16 Reddit AMA at 14:00 UTC and invited challenges to its tier list. The announcement offers a discussion forum, with an issuance decision and activation schedule still outstanding.
The decision ahead is whether the dilution saved by a lower reward budget can be reconciled with a validator set that remains viable and sufficiently independent. Until that is resolved, the existing allocation continues: validators receive issuance for their participation, while unstaked holders retain the asset without sharing in those rewards.
Source: CryptoSlate