

FILTERED RESULTS
FILTERS
•
·
·
FILTERED RESULTS
Circle, Ripple, and Standard Chartered Back OKX in Extended $25B Funding Round
NASA’s Moon Base Program Propels Rocket Lab (RKLB) Higher as Bulk Launch Deal Nears
Hard Drive Stocks Tumble as Toshiba and Seagate Battle for TDK’s Magnetic Head Unit
Uber (UBER) Acquires ezCater for $2.3B to Dominate Corporate Catering Market
Meta Collaborates with Sierra to Establish AI Business Standards
Sheikh Khalifa calls for strengthening GCC supply chain resilience
Health Incident in Siberia Raises Investor Awareness Amid Market Stability
Analysts Split on Meta’s AI Timeline: Muse Downloads Surge While Revenue Delays Loom
S&P 500 Hits First Record Since August as AI Bulls Take the Lead
Gold prices forecast to reach $5,013 per ounce in 12 months
Anthropic adds Claude integration to Google Workspace apps
Why is Aritzia stock sliding today?
Brazil reports $7.7B trade surplus for September
IEA to Meet Wednesday to Discuss Diesel, Crude Stocks Release
Gen Z’s Love of Malls Boosts NZ Stock, Defying Cost-of-Living Blues
Ships Take Long Way Around as Drought Snarls Panama Canal
Crude Oil Prices Rise Amid Escalating Tensions in the Strait of Hormuz
Prime Video Secures Exclusive Emmy Awards Broadcasting Rights Through 2032
Marvell Technology (MRVL) Eyes $70-90 Billion Revenue by 2031 as AI Chip Demand Explodes
Bolsonaro Surge in Brazil Opens Door to Commodities Trade Shift
US Treasuries Yields Fall From 2002 High as Oil Prices Dip
AlphaSense Launches SuperAnalyst AI Agent for Enhanced Market Intelligence
Federal Reserve to restructure US bank supervision model
Rain Files Application to Establish National Trust Bank in New York
Texas AG Paxton probes Fruit of the Loom, Hanes over potential toxic chemicals in children’s underwear
Florida’s Troubled Public Schools Load Up on Debt to Pay Bills
ExxonMobil looks to offshore projects in Trinidad and Tobago for next boom
OKX Secures Strategic Investment from Major Firms at $25 Billion Valuation
U.S. Electricity Consumption Expected to Reach Record Levels Due to AI and Crypto Demand
Kansas City Fed President Emphasizes Inflation Focus Amid Stable Labor Market
US power use to beat record highs in 2026 and 2027 as AI use surges, EIA says
US agency to rewrite rules to reduce vehicle headlight glare
Northeast Democrats urge Trump administration action as heating oil costs surge
Explosion Reported Near Qeshm Island, Iran
Saudi Aramco CEO: oil inventories at stress level with only 10% available
Ukrainian President Zelenskiy Warns of Imminent Russian Offensive
Oil prices stable as market weighs supply risks, rising Middle East exports
Wall Street profits soar to $45.9 billion in first half of 2026, report shows
US power demand to hit record highs in 2027 amid AI consumption, EIA says
Iran attacks more tankers in Hormuz as oil flows continue to rise
Stocks hit new record high even as consumers feel dreary
Disney Lawyer Says FCC Holding a ‘Guillotine’ Over ABC’s Head
US Stock Indices Reach Record Levels Amid Divergence in Technology Sector
Google and Constellation Energy Strike a Sweeping Nuclear-Power Deal
Emerging-Market Assets Extend Gains as US Yields Decline
US Treasury Sells $58 Billion in Three-Year Notes at 4.932% Yield
European shares rise as retreating bond yields and oil prices boost risk appetite
S&P 500 Climbs to Record High on Earnings Optimism: Markets Wrap
McDonald’s Franchisees Balk at Costly Bill to Upgrade Stores
Man Group Disputes View That High Inflation Is Bad for Bonds
EIA expects a mixed picture for US households winter fuel costs this year
US EIA hikes oil price forecasts again as Iran war drains global stockpile
Google launches EmbeddingGemma 2 for on-device multimodal search
General Medicine raises $120 million to expand healthcare store
BoJ may signal underlying inflation has hit 2% goal
Asian stocks mostly up after tech-led Wall Street record
Robo.ai (AIIO) Reports $100M+ September Sales, Eyes $600M by End of 2026
Tech Giants Deploy $76 Billion in AI Infrastructure as Nvidia (NVDA) Approaches $6 Trillion Valuation
U.K. stocks higher at close of trade; Investing.com United Kingdom 100 up 0.43%
Spain stocks higher at close of trade; IBEX 35 up 0.75%
Xanadu Quantum (XNDU) Shares Surge on GlobalFoundries Manufacturing Agreement
How Trump’s Tariff War With Canada Ensnared the Can-Am Spyder
Ares Faces 50% Loss on Cash Piled Into TalkTalk With BT Deal
Anduril plans shipyard to manufacture parts for US Navy’s top submarines
Gold is a good diversification strategy for central banks – Nagel
Emerging Assets Extend Rally for as Oil Rally, US Yields Drop
The Future Is Universal Health Insurance
Mapping How South America’s Right-Wing Shift Has Reached Brazil
Anthropic Expands Claude Startups Program to Engage Founders and Fast-Growing Companies
Palantir (PLTR) Stock Analysis: Technical Levels to Watch After 93% Revenue Surge


Key Takeaways
- PLTR currently trades at approximately $192.35, roughly 8% beneath its 52-week peak of $207.52.
- The company delivered $1.94 billion in quarterly revenue, marking a 93% year-over-year increase.
- U.S. government segment revenue climbed 90% to reach $809 million.
- Management elevated full-year revenue projections to approximately $8.15-$8.16 billion.
- Wall Street coverage includes 23 Buy ratings, 10 Hold ratings, and 3 Sell ratings, with a consensus target of $195.33.
- British authorities are examining domestic alternatives to replace Palantir in NHS and defense applications.
Shares of Palantir (PLTR) are currently changing hands around $192.35, positioned approximately 8% under the stock’s 52-week pinnacle of $207.52. The equity has demonstrated consistent upward momentum since trading near $160 back in August.

Palantir Technologies Inc., PLTR
The recent rally follows another impressive quarterly performance. The software giant reported $1.94 billion in top-line revenue during the most recent period, representing a 93% surge compared to the same quarter last year.
The government segment in the United States demonstrated particularly robust expansion, with revenue jumping 90% to $809 million. In response, company leadership boosted their full-year revenue outlook to a range of roughly $8.15 billion to $8.16 billion.
This represents a substantial upgrade from previous estimates. The revision demonstrates that Palantir’s artificial intelligence initiatives are generating tangible commercial agreements rather than remaining confined to experimental deployments.
Defense contracts and sovereign AI gaining traction
The Department of Defense designated Palantir’s Maven AI platform as an official program of record during the first half of this year. This classification embeds the technology deeper into long-term U.S. military infrastructure.
The company also secured a $300 million contract with the United States Department of Agriculture. Palantir continues expanding its portfolio of government engagements beyond its established client base.
An emerging strategic direction involves sovereign AI capabilities. Palantir formed an alliance with Armada to integrate its Sovereign AI Operating System with client-owned infrastructure that operates entirely independent of public cloud platforms.
This architecture enables governments and enterprises to maintain complete jurisdiction over their AI frameworks and sensitive information. It marks a significant departure from dependence on AWS or Azure environments.
The company has simultaneously deepened its collaboration with Fujitsu, which will implement AIP and Foundry solutions. Fujitsu has already leveraged the platform to integrate data streams from over 3,000 suppliers and 18 manufacturing facilities for a Japanese industrial client.
International headwinds and valuation concerns mounting
International expansion efforts face some obstacles. United Kingdom officials are reportedly evaluating British-developed alternatives to Palantir for portions of NHS technology infrastructure and defense systems.
Research conducted by the Financial Times revealed that over 20 NHS trusts have discontinued certain Palantir waiting-list management tools. This development represents a meaningful setback to the company’s global growth narrative.
According to MarketBeat data, 36 analysts maintain active coverage on PLTR. The breakdown shows 23 Buy or Strong Buy recommendations, 10 Hold ratings, and 3 Sell ratings, producing a Moderate Buy consensus overall.
The mean price objective stands at $195.33, marginally above current trading levels. Individual targets span from a peak of $255 down to a floor of $80, illustrating the dramatic disagreement between optimistic and pessimistic perspectives.
UBS and DA Davidson both recently elevated their price objectives to $250. Rosenblatt maintained its $225 target, while Goldman Sachs preserved a Neutral stance.
Valuation metrics represent the primary point of contention. MarketBeat data indicates Palantir trades at approximately 162 times trailing earnings, with total market capitalization exceeding $450 billion.
That premium appears steep for any software business, even one delivering revenue expansion approaching 90%. The optimistic thesis depends on Palantir maintaining this growth trajectory for an extended period to validate current pricing.
From a technical perspective, PLTR encounters overhead resistance in the $198 to $205 region, an area encompassing both an ascending channel boundary and previous supply zones. A sustained break above this range could establish a runway toward $220-$225.
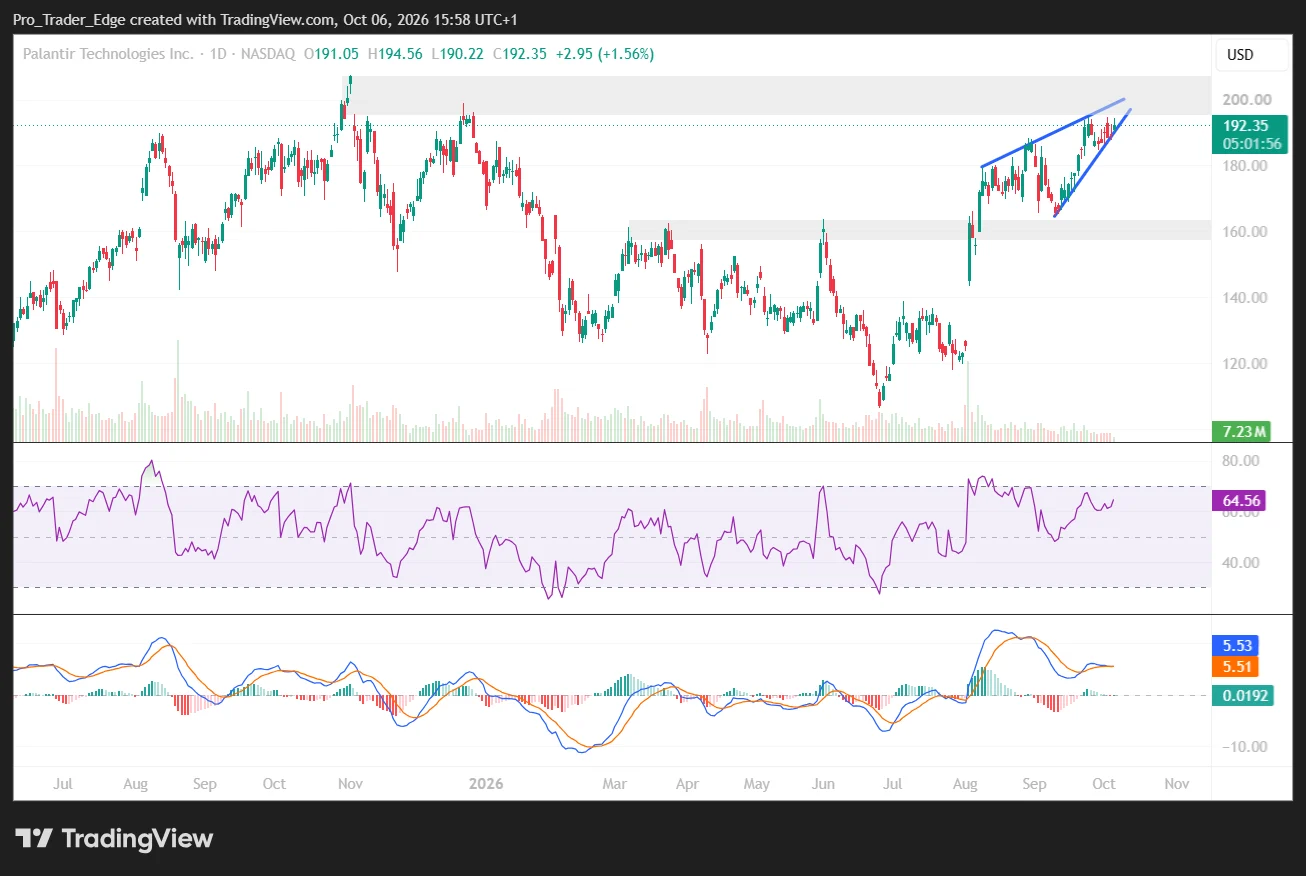
Initial support is located around $180 to $183, where the near-term uptrend line presently tracks. Failure to hold above $180 would increase the probability of a more substantial retracement toward $160.
The Relative Strength Index currently registers 64.56, indicating solid momentum without reaching overbought territory. The MACD indicator recently crossed into positive territory, though the histogram remains relatively neutral.
Trading activity has remained relatively subdued during the recent advance toward $200. A breakout accompanied by elevated volume would signal stronger conviction than a move on below-average participation.
Source: Parameter